
What could cause our loan to get denied late in the process?
Most late denials come from something that changed after the lender’s first decision. The usual causes are new debt, a job change, money the lender can’t trace, a low appraisal, or a problem with a condo building.
You avoid most of them by changing nothing about your money or your job without calling your loan officer first. In Massachusetts, a denial that comes after your contract’s mortgage commitment date can put your deposit at risk.
What Does the Lender Re-Check Before Closing?
New debt causes the most trouble. Under Fannie Mae’s rules, a lender that finds new debt or lower income any time up to closing has to redo your debt-to-income math. If the numbers move too far, the loan goes back through underwriting. Fannie says undisclosed debt has been the top serious defect in the loans it reviews since 2021, and the usual culprit is a car loan or lease.
You’ll hear that one credit check will kill your loan. It won’t. The CFPB says an inquiry typically has a small effect on your scores, and the lender will ask if it turned into a new account. The lender also re-checks your job, within 10 business days of closing on most conventional loans, and any change there gets a full second look.
Money moves count too. The lender will ask where any large deposit came from, and money it can’t trace doesn’t count toward closing. A gift needs a signed letter and a paper trail, so a wire works and an envelope of cash doesn’t.
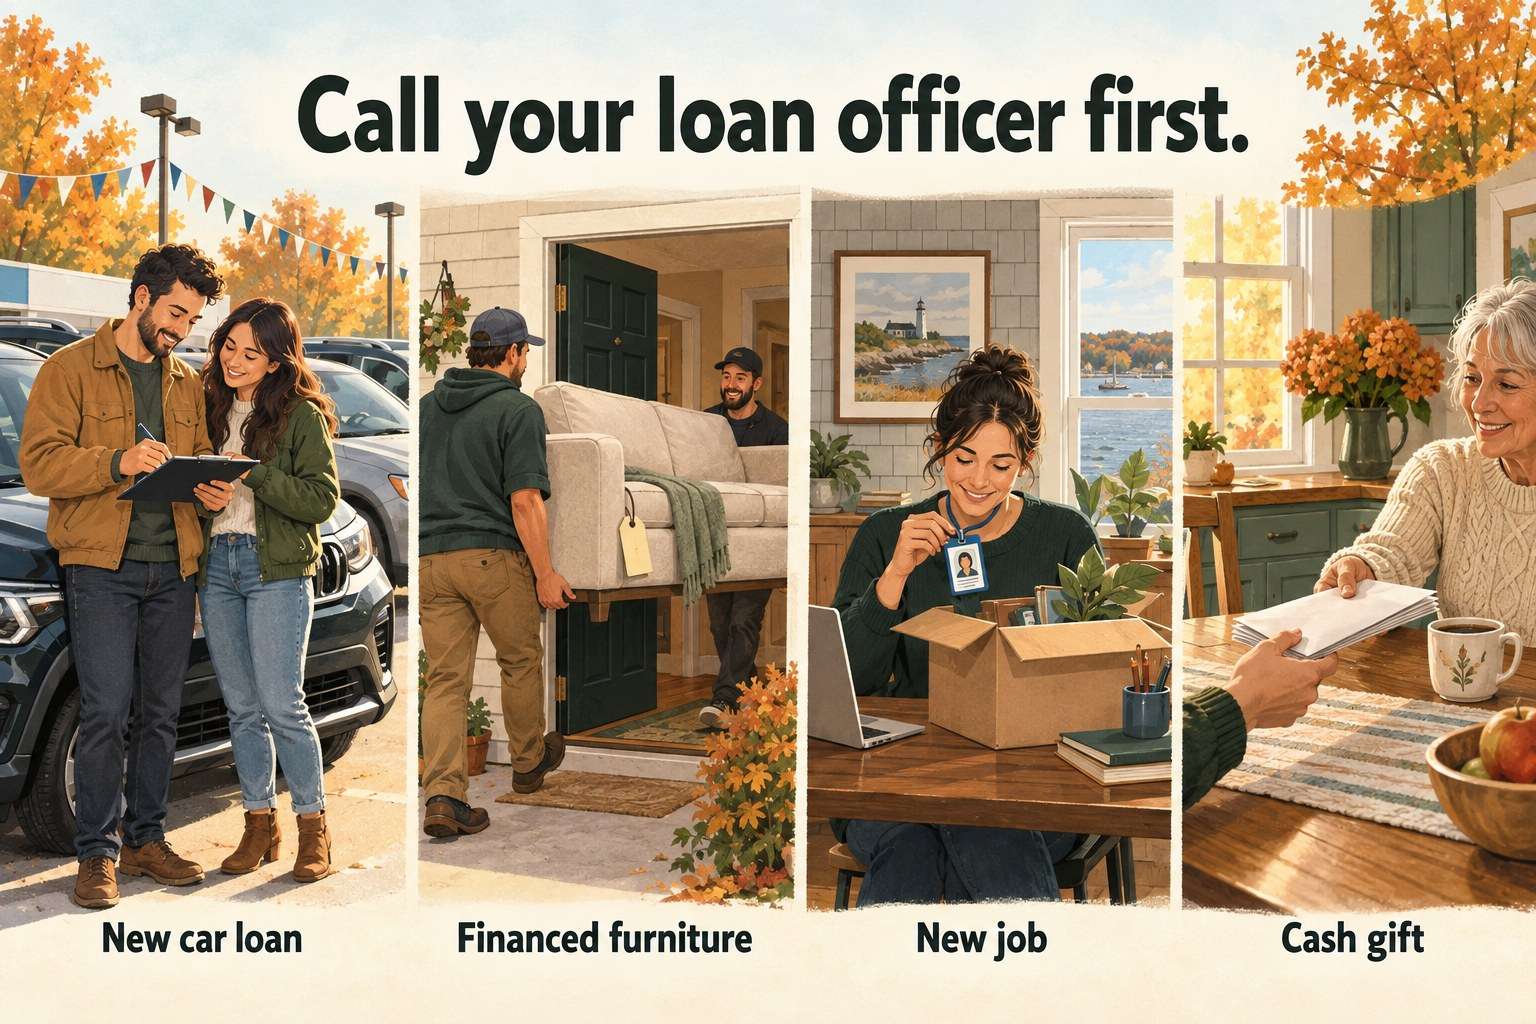
Call your loan officer before you do any of these:
- Apply for a car loan, a lease or a new credit card
- Finance furniture or appliances
- Change jobs, or change how you’re paid
- Deposit a large sum, including a cash gift from family
What If the Problem Is the Appraisal or the Building?
The lender figures your loan-to-value on the lower of the price or the appraised value, so a low appraisal makes the same loan a bigger share of the home. You’ll hear that a low appraisal means the deal is off. It doesn’t have to end there. You can bring more cash, renegotiate the price, or ask the lender to reconsider. Fannie Mae allows one reconsideration per appraisal, backed by up to five comparable sales.
A condo gets a second review, of the building itself. A project with a pending lawsuit over safety or structure, or critical repairs the association hasn’t made, can be ineligible even when you qualify easily. Get the condo documents to the lender early, and read our guide to condo warrantability.
If Our Loan Is Denied, Do We Lose Our Deposit?
You’ll hear that a denied loan means your deposit comes back. That’s true only before the commitment date, depending on your contract. Under the standard Massachusetts purchase and sale form, you can end the deal and get your deposit back if the lender hasn’t committed by that date. You have to give written notice before it passes. A Massachusetts appeals court said a buyer who gives no notice and asks for no extension “runs the risk of losing his deposit.”
The commitment letter feels like the finish line. The weeks after it are when buyers go shopping for the car. A commitment can carry its own conditions, so have your real estate attorney read them before that date.
A lender that says no has to send a written notice with the specific reasons, or tell you how to get them. GoldCoast is a broker, so the lender underwrites your file, issues the commitment and makes the final call. Before you sign for a new loan or take a new job, we can ask the lender how it changes your file. If one lender says no, we can look at another. A pre-qualification is free and commits you to nothing.