
Can we lock our rate and still close when our lease ends?
Usually yes, but the lender issues the rate lock, not a broker, and locking today is that lender’s call. Once it happens, your Loan Estimate prints the expiration date and time on page 1, and that is the date to schedule against.
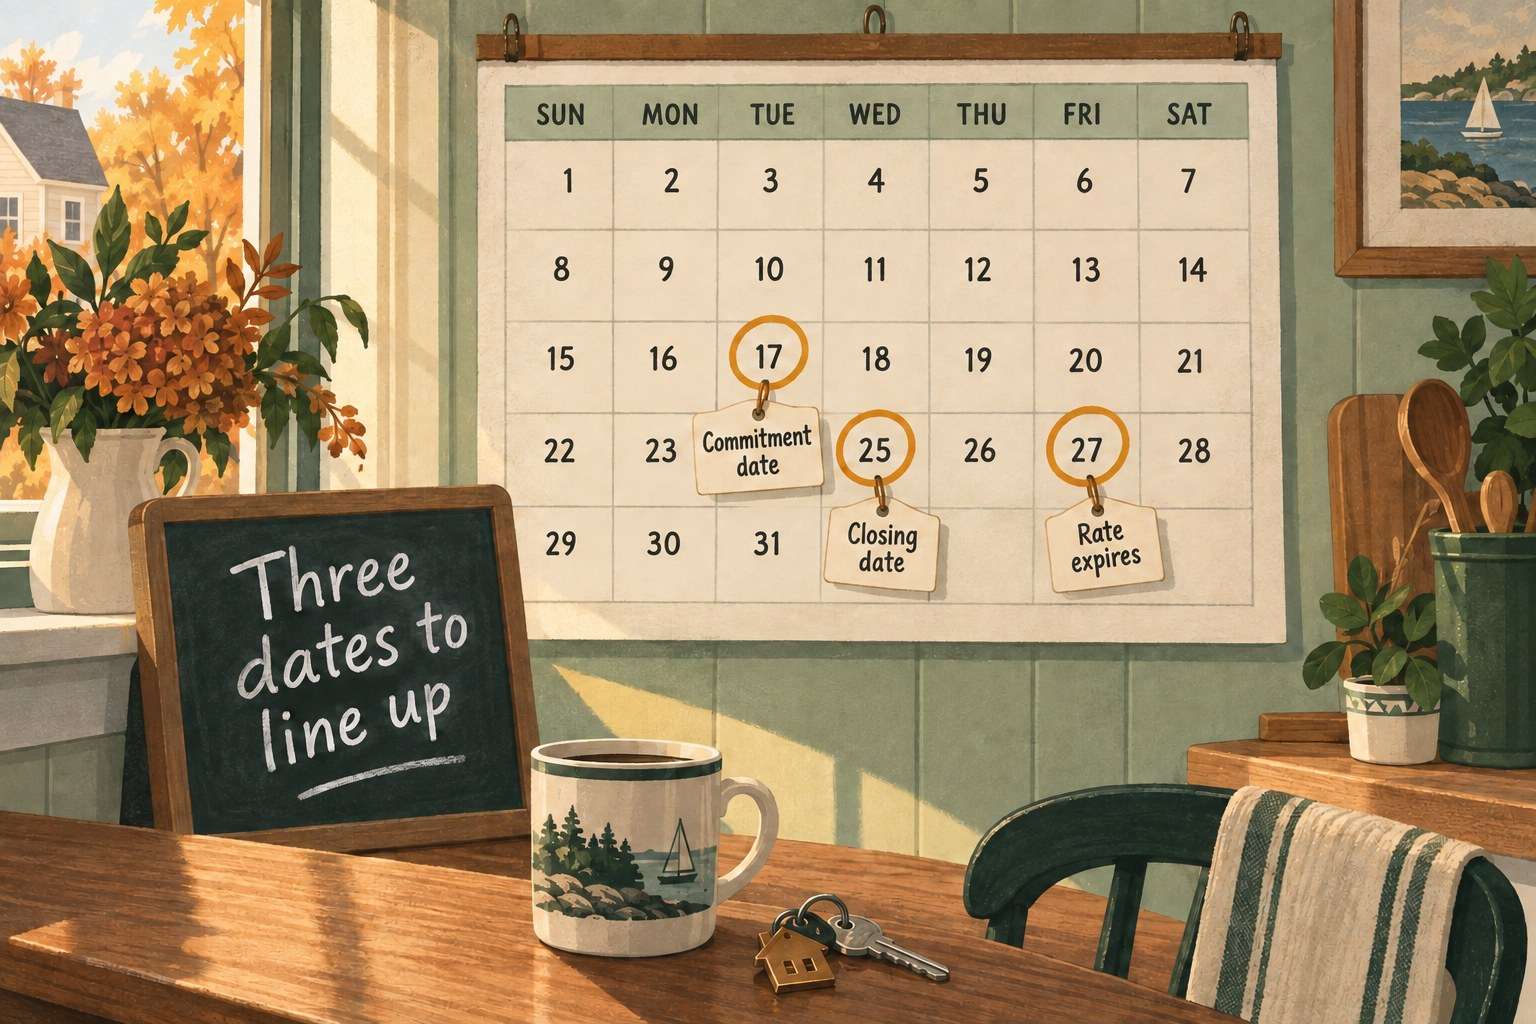
The closing date and the mortgage commitment date live in your purchase and sale agreement. The lock expiration doesn’t, so you have three dates to line up.
Who Issues the Rate Lock, the Broker or the Lender?
You’ll hear buyers say “our broker locked our rate.” In Massachusetts that sentence can’t be true. State rules make it a prohibited practice for a mortgage broker to issue a rate lock commitment, or to suggest it can lock a rate for you. Only a lender issues one, and the request form a broker hands you has to say so. “This is a request, not a commitment, to lock your interest rate with a mortgage lender.”
The same rule says what a broker can do. GoldCoast can negotiate your loan terms, including the interest rate, and carry your request to the lender. The lender underwrites your file, issues the lock and prices any extension.
Locked feels like settled. It isn’t. The lender hasn’t approved or denied your loan yet, and the rate holds only if you close in time and nothing on your application changes. And a lock cuts both ways, because it shields you if rates rise and shuts you out if they fall.
Which Date Do We Schedule Against?
The lock expiration. Federal rule requires page 1 of your Loan Estimate to state if your rate is locked and, if it is, the date and time that ends, with the time zone. A second date-and-time stamp in the same box covers your estimated closing costs instead. After the lock, the lender has to send you a revised Loan Estimate within three business days, so that document arrives on its own.
Federal rule fences in the other end too. You have to receive the Closing Disclosure three business days before closing, and Saturdays count for that clock. Moving the closing date by agreement doesn’t restart the wait.
You’ll also hear that a locked rate protects your deposit. It doesn’t. The three dates do three different jobs.
- The closing date. You and the seller set it in your contract, and it moves only in writing.
- The mortgage commitment date. Also in that contract, usually earlier, and your deposit turns on it.
- The rate lock expiration. The lender sets it, and it touches nothing in your contract.
Under the standard Massachusetts form you keep your deposit only by giving written notice before the commitment date passes. Let it go by, and under Tremouliaris v. Pina you risk losing the deposit and having to buy the house anyway. Ask your real estate attorney to read those dates with you.
When Do We Tell Our Landlord?
Later than you think. The date you need is in your own lease, in the first ten or fifteen lines. A lease for a fixed term ends on its stated date and needs no notice from you. A self-extending lease renews for another year unless you give notice, usually about a month before it ends, which often falls before you know your closing date. Put that date on the calendar this week, next to the lock expiration.
Go month to month to cover a closing that might slip and the notice duty becomes yours. Massachusetts asks you for written notice of thirty days or one full rental period, whichever runs longer. And don’t count your security deposit as closing money, because your landlord can take up to thirty days after you move out to return it. Our guide to renewing versus buying covers the rest of that decision.
GoldCoast is a mortgage broker, so the lender makes those calls. What we can do is watch all three dates at once and tell you which one is about to pass. A pre-qualification is free and commits you to nothing.